The 6 Best Personal Loans in Tennessee for 2026
Last updated: 2026-11-12
Picking a loan in Tennessee usually comes down to two things: your credit score and how fast you need the money. If your credit is great, a national bank will likely give you a low-interest loan. But if you’re dealing with an emergency or your credit history is a bit messy, you’ll probably need to look at specialized lenders or installment loan providers instead.
1. LightStream
2. LoansTN
3. PaydayChampion
4. Navy Federal Credit Union
5. GreendayOnline
6. Citibank
When you’re comparing these, keep a close eye on the APR and how fast they actually send the funds. A low interest rate is great if you’re consolidating debt, but it won’t help much if you need cash by tomorrow morning. This guide looks at the main players in Tennessee to help you figure out which path makes sense for your wallet.
How We Compared Tennessee Loan Options
We looked at how these providers serve Tennessee residents, how easy the application process is, and how quickly they get money into your account. We specifically searched for lenders that are upfront about credit requirements and whether they’ll do a hard credit pull just to give you an initial quote.
We also checked the loan amounts. A lender that only does tiny micro-loans isn’t going to help if you’re trying to pay off a massive credit card balance. On the flip side, a big bank might be way too slow when you have a sudden repair bill to pay. Our list balances accessibility, speed, and cost for different types of borrowers.
| Provider | Loan Amount Range | Speed of Funding | Credit Requirements |
|---|---|---|---|
| LightStream | see site | see site | see site |
| LoansTN | $500 – $35,000 | 24-Hour Funding | No hard credit pull |
| PaydayChampion | $100 – $5,000+ | Minutes | No credit check |
| Navy Federal Credit Union | see site | see site | see site |
| GreendayOnline | $100 – $5,000 | Same day | Bad credit welcome |
| Citibank | see site | see site | see site |
Understanding Loan Types: Term Length and Interest Impact
Before diving into specific providers, it is crucial to understand the two primary structures you will encounter in the Tennessee lending market: installment loans and payday/short-term loans. The distinction between them can change your financial trajectory for years.
Installment Loans: These are what most people think of when they say “personal loan.” You receive a lump sum upfront and pay it back in fixed monthly installments over a set period, usually 12 to 60 months. Because the repayment is structured, the interest rates are generally lower. This is the ideal vehicle for debt consolidation or a major home improvement project. If you borrow $5,000 at a 10% APR over three years, your monthly payment stays predictable, allowing you to budget effectively.
Short-Term/Payday Loans: These are designed for immediate, high-pressure situations, such as an unexpected car repair that prevents you from getting to work. These loans are much smaller and have much shorter repayment windows. The trade-off for the speed and high accessibility is the cost. Interest rates can be significantly higher than traditional installment loans. While they solve a problem today, they are best used as a temporary bridge rather than a long-term financial strategy.
Key Comparison: Term Length vs. Total Cost
| Feature | Installment Loan | Short-Term/Payday Loan |
|---|---|---|
| Repayment Period | Months to Years | Days to Months |
| Typical APR | Moderate to Low | High to Very High |
| Primary Use Case | Consolidation, Large Purchases | Emergency Expenses |
1. LightStream
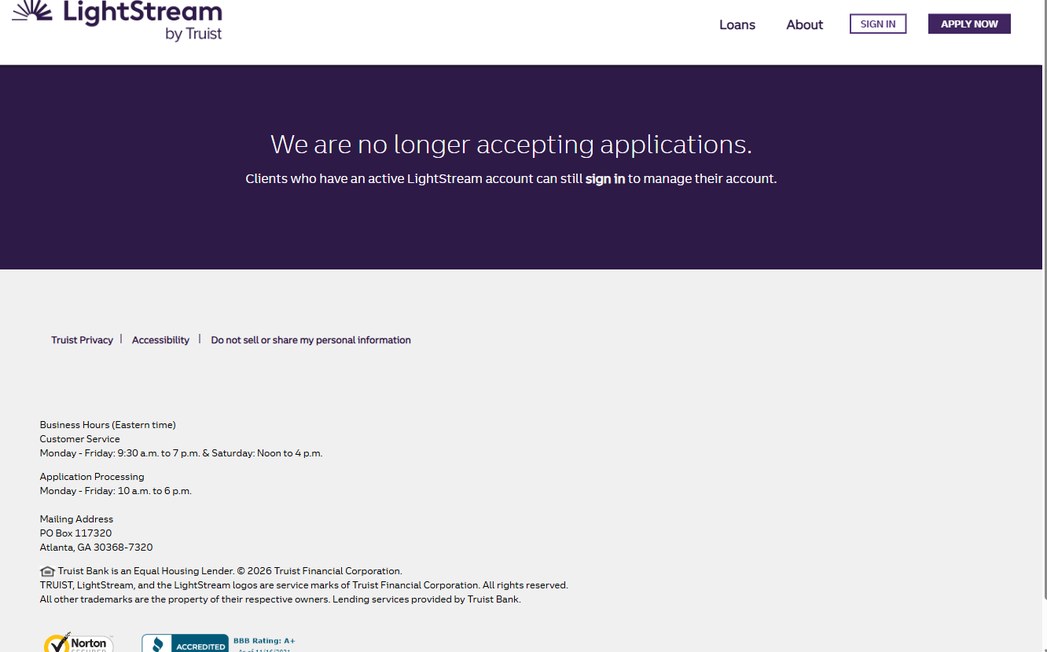
LightStream is a Truist service that targets borrowers with established credit. You can use their loans for just about anything, from fixing up your house to paying off other debts. They’re a solid pick if you want a traditional, professional banking experience.
Since they’re part of Truist, they’re very stable. The downside? They aren’t for everyone. If your credit is currently a struggle, the application might be much harder than what you’ll find elsewhere on this list. They work best for people who can snag competitive rates based on their existing financial standing. For example, if you have a score above 700, you might find their rates significantly lower than a local non-bank lender, saving you hundreds in interest over the life of the loan.
Pros:
- Versatile use of funds for practically anything
- Part of a major banking institution
Cons:
- Currently not accepting new applications (per homepage)
2. LoansTN
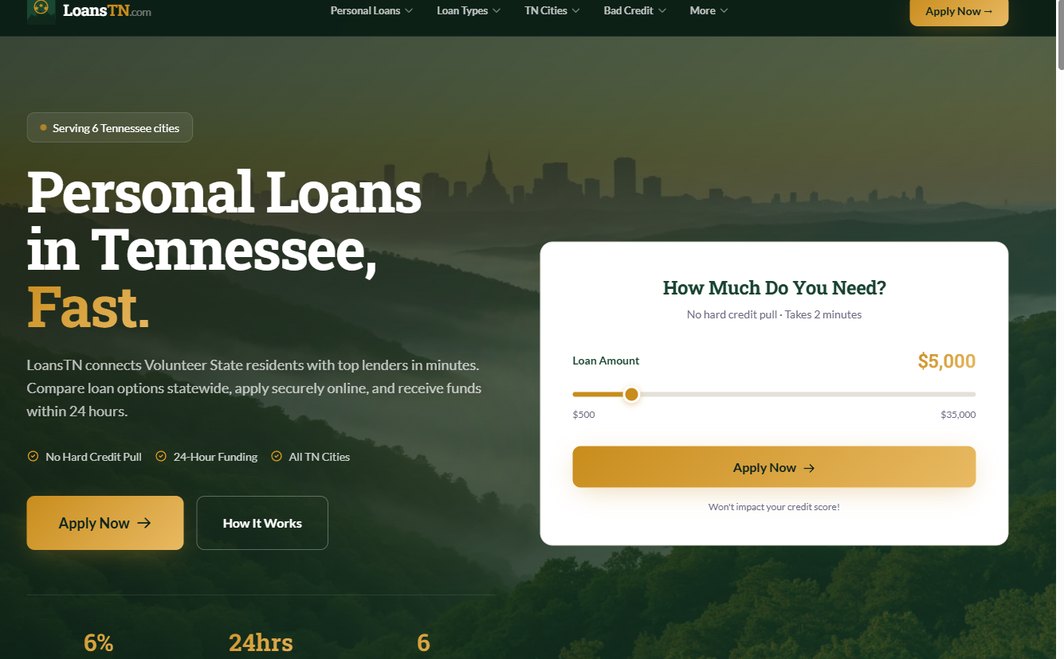
LoansTN is built specifically for people in Tennessee. They act as a bridge between residents and top lenders to speed things up. This is a good option if you want to see different choices across the state without filling out dozens of separate forms. Whether you are in Nashville, Memphis, or a more rural county, their network is designed to reach Tennessee residents efficiently.
One big plus of using loanstn.com is that you can check your rates in about two minutes without a hard credit pull. That means you can see your options without hurting your score. They offer 24-hour funding and cover many cities across the state. This “soft pull” mechanism is a vital tool for comparison shopping, as it allows you to gauge your borrowing power without the risk of a sudden dip in your credit score.
Pros:
- No hard credit pull for initial rate checks
- Fast 24-hour funding
- Specific to Tennessee residents
Cons:
- Requires a 2-minute application process even for simple checks
3. PaydayChampion
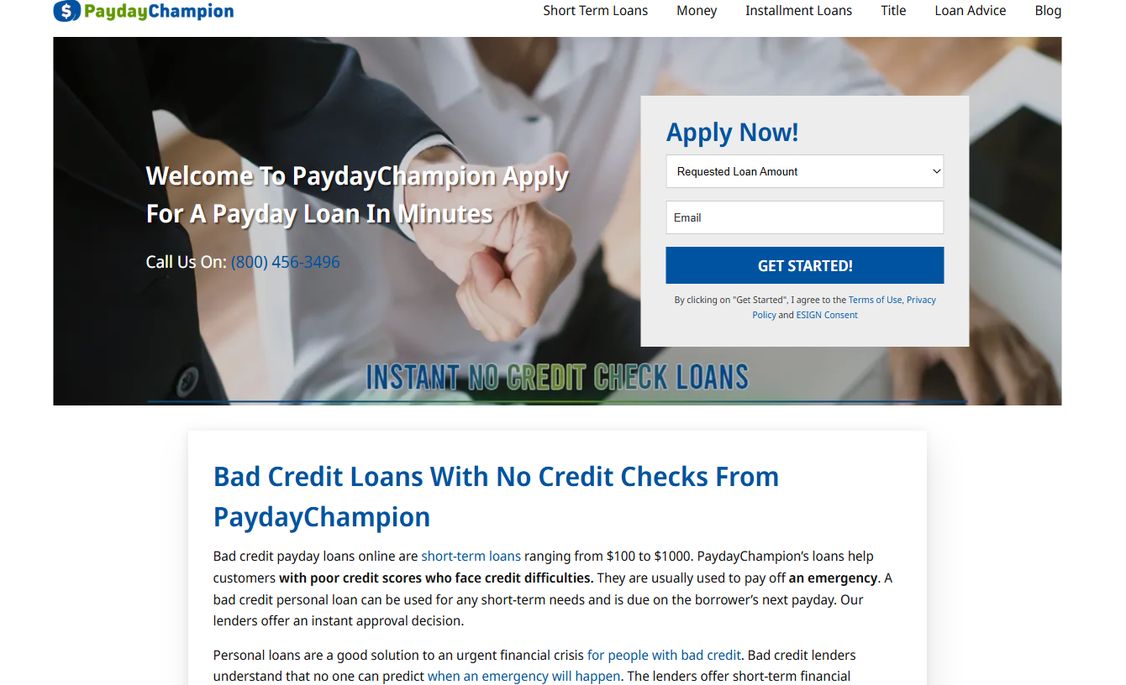
PaydayChampion is made for emergencies. They specialize in short-term installment and payday loans for people with poor credit. If you’re facing a sudden expense and can’t get a loan from a traditional bank, these lenders are designed to help you get cash fast.
Their loans usually go from $100 up to $5,000 or more. They focus heavily on “guaranteed approval” for people with bad credit. This makes them a good fallback when other doors are closed, but you should be careful about the terms that come with short-term, high-interest lending. Because these loans are designed for rapid turnover, the repayment schedule is aggressive, so ensure you have a plan to pay it back before the next cycle begins.
Pros:
- High accessibility for bad credit borrowers
- Fast application process for quick cash
Cons:
- Designed for short-term use rather than long-term debt
4. Navy Federal Credit Union
Navy Federal Credit Union is a member-owned institution. While they’re famous for their services for the military, they offer plenty of other things like auto loans and credit cards. They’re a great choice if you’re eligible for membership. Membership is typically open to active-duty military, veterans, and their family members, but it is worth checking if your specific connection qualifies you.
They have a 90-day preapproval option on certain loans, which gives you a bit of time to think about a purchase before you’re fully committed. It’s a much more relaxed way to shop for financing than the high-pressure vibe you get from some online lenders. This is particularly useful if you are browsing for an auto loan and want to know your budget before you step onto a dealership lot.
Pros:
- 90-day preapproval gives you latitude
- Credit union structure often benefits members
Cons:
- Membership requirements apply
5. GreendayOnline
GreendayOnline focuses on small payday and installment loans. Their main goal is helping people get emergency cash quickly. They offer between $100 and $5,000 and do everything online to keep the process simple. Their digital-first approach means you don’t have to drive to a physical storefront in a different county to get your funds.
They accept people with bad credit and aim for same-day funding. The process is very streamlined, you can often go from application to approval in just a few minutes. It’s a specialized service for anyone who needs money in their account as fast as possible, such as covering an unexpected medical co-pay or a utility bill that is due immediately.
Pros:
- Very fast approval decisions
- No hard credit checks
Cons:
- Limited to smaller loan amounts compared to major banks
6. Citibank
Citibank is a massive global bank that offers standard personal loans alongside its usual banking products. They’re a mainstream option if you want a traditional relationship with a large-scale institution. They also offer various credit cards and investment options. They are a “big bank” solution for those with strong, stable financial histories.
If you already bank with Citi, you might get access to certain rewards and benefits. However, if you need “no credit check” loans or instant emergency cash, a major bank like Citibank might not be the most flexible choice for your immediate needs. Their approval process often involves more rigorous documentation and verification steps than specialized online lenders.
Pros:
- Extensive range of financial services
- Established reputation and stability
Cons:
- Likely requires much higher credit standards
How to Choose and Mistakes to Avoid
Before you sign anything, decide if you need a long-term loan or just a short-term fix. According to wallethub.com, the best personal loans in Tennessee can have APRs ranging from 6.49% to 24.89%. A high APR might solve a problem today, but it could create a much bigger one next month. If you’re looking to consolidate debt, aim for the lowest rate you can find to ensure the interest isn’t eating up your monthly cash flow.
Don’t make the mistake of only looking at the monthly payment. The total cost of the loan is what actually matters. Always check the total interest you’ll end up paying over the life of the loan. For example, a $2,000 loan with a $100 monthly payment sounds manageable, but if that loan lasts for 36 months, you’ve actually paid $3,600 for that $2,000. That’s $1,600 in interest alone. Always calculate the “total of payments” before signing.
Also, stay away from lenders that don’t disclose their terms clearly. If you can’t find the APR or the total repayment amount easily, move on. Legitimate Tennessee lenders are required to be transparent about their costs. If a lender pressures you to sign quickly without reading the fine print or uses “teaser rates” that jump significantly after a few months, walk away.
The Tennessee Borrower’s Pre-Loan Checklist
To ensure you are making the smartest financial move, run through this checklist before you submit your final application with any Tennessee lender:
- Verify the APR: Is the Annual Percentage Rate inclusive of all fees? The APR is a more accurate measure of cost than the base interest rate.
- Check for Prepayment Penalties: If you get a bonus at work or a tax refund, can you pay the loan off early without being charged a fee? Avoiding these penalties can save you significant money.
- Review the Funding Timeline: Does the lender deposit funds on a business day or a weekend? If you need the money for a Saturday emergency, a “same-day” lender might still take 48 hours to process the ACH transfer.
- Confirm Identity Requirements: Do you have your Tennessee ID, Social Security number, and most recent pay stubs ready? Having these prepared prevents delays in the approval process.
- Evaluate the Total Repayment Amount: Multiply your monthly payment by the total number of months. Compare this to the amount you are borrowing to see the true cost of your credit.